
Thailand’s Securities and Exchange Commission opened a consultation on 22 October 2026 about clearer individual provident-fund statements. The proposal would bring a member’s total portfolio value, investment allocation, performance by policy and personal rate of return into a more useful view.
It would also introduce a minimum retirement savings target and a link to an online retirement-planning tool. These ideas are not final rules. The consultation remains open until 20 November 2026, so readers should treat the details as a proposal rather than a guaranteed statement format.
Quick Guide
| Status | Public consultation, not a final rule. |
|---|---|
| Consultation closes | 20 November 2026. |
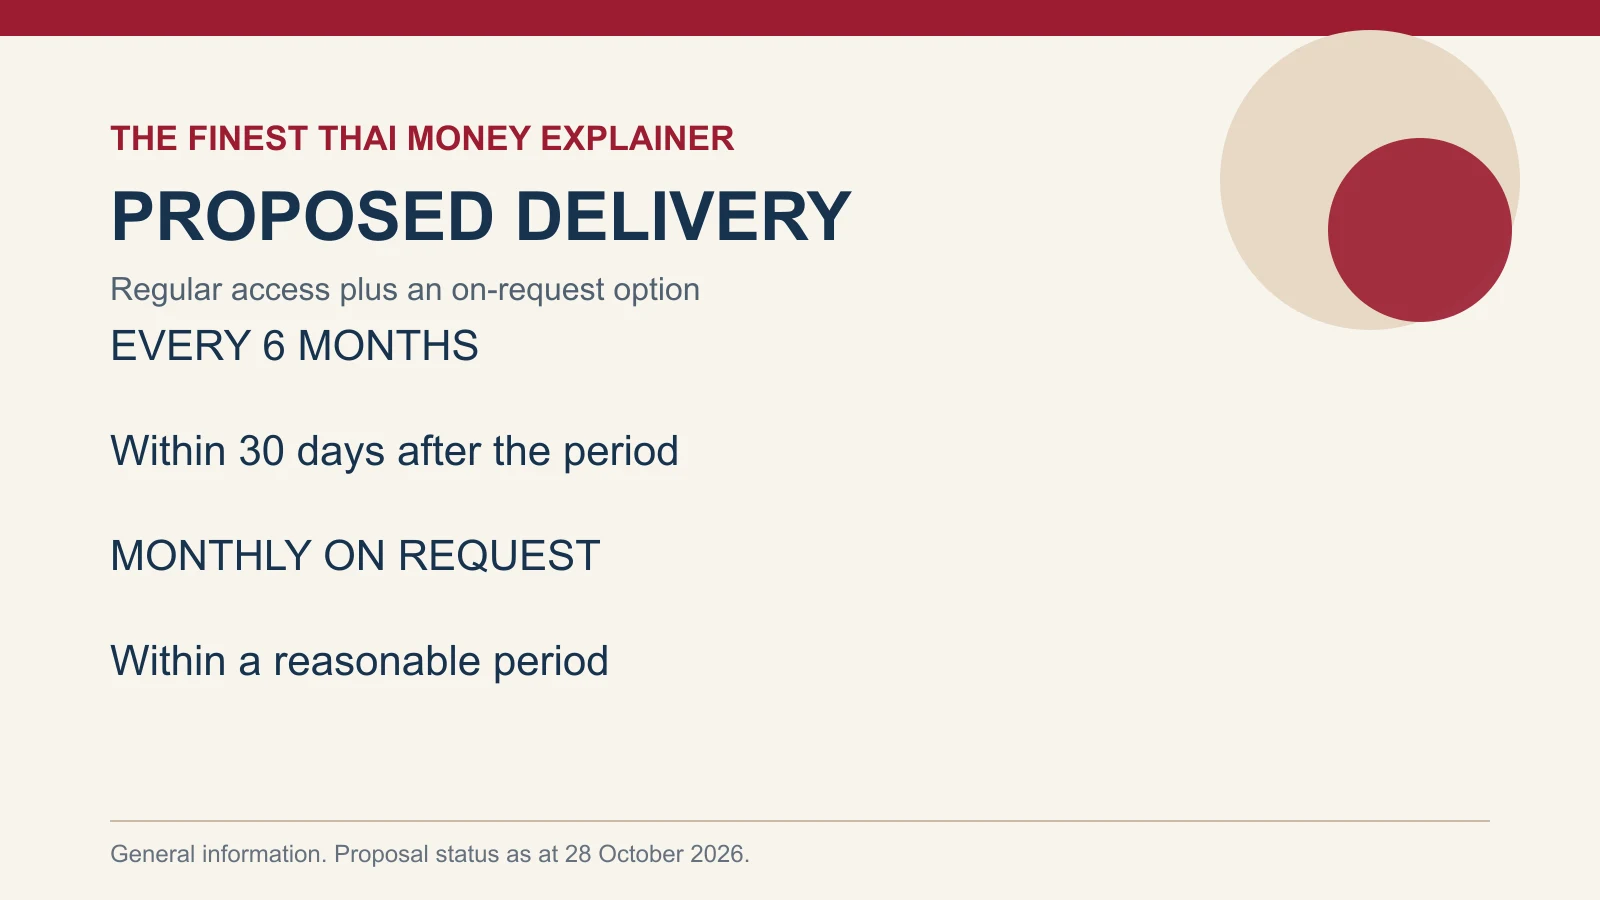
| Regular timing | At least every six months, within 30 days after the end of the period. |
| On request | A monthly statement within a reasonable period. |
| Proposed additions | Total value, allocation, performance, personal return, minimum retirement target and a planning-tool link. |
A Clearer Total Position
Many members can see contributions or a current balance without immediately understanding the whole portfolio. The proposal aims to make the total value explicit and connect it to the policies in which the money is invested. That would reduce the need to reconstruct a position from separate pages or codes.
A total figure still needs context. Members should look at the statement date, contribution period and whether pending transactions are included. A balance is a snapshot, not a promise of what the fund will be worth at retirement.
Allocation and Performance
Showing allocation by investment policy can help a member see whether the portfolio is mainly in bonds, equities, mixed assets or another mandate. Performance by policy would then make it easier to identify which part of the portfolio drove a gain or loss.
Performance should be read over a suitable period and against the policy’s objective, not judged from one month. A volatile growth policy and a conservative policy are designed for different jobs. Switching solely because one line recently fell can crystallise a short-term reaction into a long-term decision.
The Personal Rate of Return
A personal rate of return differs from a fund’s published performance because it reflects the timing of the member’s own contributions, transfers and withdrawals. Two people in the same policy can therefore see different personal outcomes.
The value of that number lies in interpretation. It can help a member compare their actual experience across periods, but it does not remove market risk or predict future returns. If the calculation method is unclear, ask the fund or employer for an explanation before making changes.
A Retirement Target
The proposed minimum retirement savings target adds a planning signal to the statement. It could help a member see whether the current path is broadly aligned with an estimated need, especially when paired with the proposed online tool.
Any target depends on assumptions such as retirement age, inflation, salary growth, future contributions and investment returns. Treat it as a prompt for a fuller plan, not a personalised guarantee. Review debts, emergency savings, insurance and other retirement assets alongside the provident fund.
Timing and Member Requests
The consultation describes statements at least every six months, delivered within 30 days after the period ends. It also contemplates a monthly statement on request within a reasonable period. That gives regular savers a baseline while allowing closer monitoring when needed.
More frequent access does not mean more frequent trading is wise. A monthly statement can be useful after a job change, policy switch or transfer. For routine retirement saving, a disciplined periodic review often produces better decisions than reacting to every market movement.
Make It Work
Members can use current statements more effectively now by checking personal details, employer and employee contributions, fees, policy allocation and beneficiary information. Report errors promptly and keep a copy of any request.
Anyone responding to the consultation should distinguish a disclosure problem from an investment preference. Clearer information helps, but the right contribution rate and asset mix still depend on the member’s circumstances and risk tolerance.
Continue Exploring
Continue with Thailand money guides, compare banking and card coverage, and keep Thailand cost-of-living guides nearby for the rest of the trip.
FAQ
Are the new statement requirements final?
No. The SEC announcement describes a consultation that closes on 20 November 2026.
What is a personal rate of return?
It reflects the timing and amount of an individual member’s own cash flows, not only the fund policy’s headline performance.
Would members receive statements every month automatically?
The proposal describes at least six-month statements, with a monthly statement available on request within a reasonable period.
Practical Information
This article is general information, not personal financial advice. Use the current statement, ask the fund for clarification and consider regulated advice for decisions with long-term consequences.